Market Overview: Defining the Scope of the Court Resurfacing Service Market
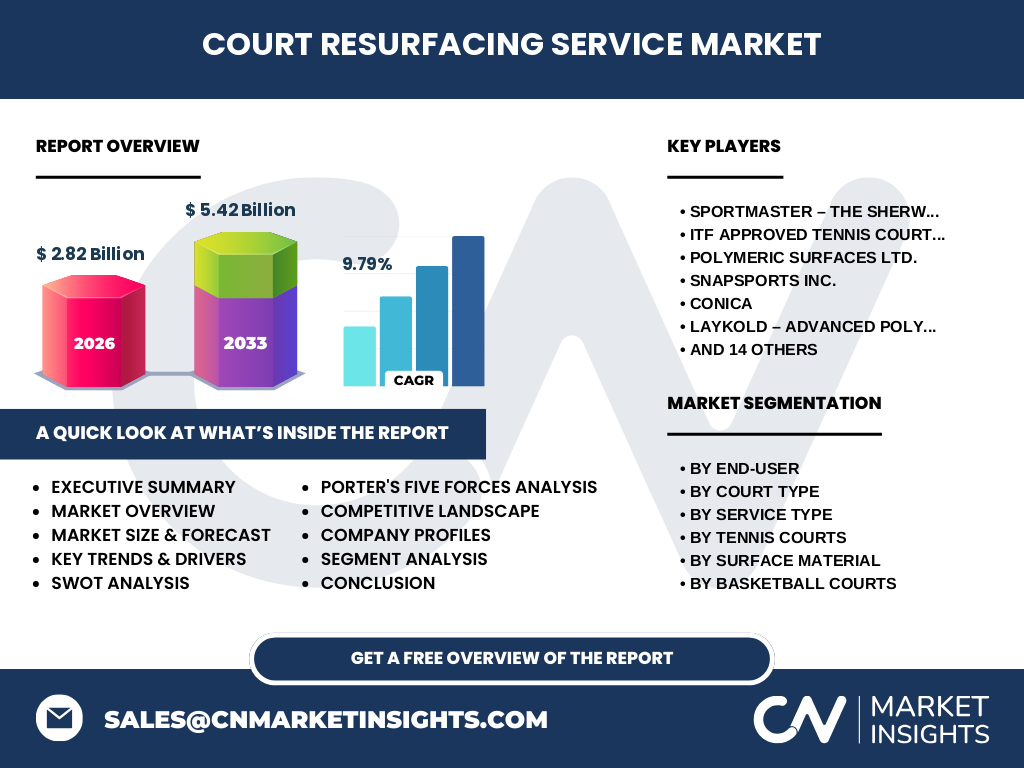
The Court Resurfacing Service Market represents a critical infrastructure sector valued at $2.82 Billion as of 2026. It encompasses professional installation, restoration, and maintenance services for diverse athletic venues. Beyond simple coating, this market is defined by the technical application of acrylic, synthetic, and modular materials, ensuring regulatory compliance with standards set by bodies like the ITF for safety, playability, and long-term asset lifecycle management.
Structural Growth Drivers, Restraints, and Opportunities
Primary drivers include the accelerated adoption of pickleball and aging public infrastructure requiring urgent rehabilitation. While logistical hurdles regarding raw material procurement for polyurethane surfaces persist, the opportunity lies in high-performance acrylic systems. Our analysis suggests that providers leveraging sustainable, low-VOC coatings will mitigate environmental regulatory pressures, turning potential compliance costs into a competitive advantage for municipal contract bidding.
Emerging Trends and Strategic Growth Patterns
A pivot toward Multi-Sport Courts is reshaping revenue models. We observe a transition from single-use clay or grass surfaces to versatile modular tile and synthetic solutions. This trend, driven by school and community requirements for flexible space, allows operators like SnapSports Inc. to capture higher value per square foot while catering to the rapidly expanding, demand-driven ecosystem of recreational multi-use facilities.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic triggered a surge in demand for outdoor recreational spaces as indoor venues shuttered. This shift forced rapid operational pivots toward outdoor concrete and asphalt court conversions. Post-pandemic recovery has been robust, characterized by a backlog of resurfacing projects as municipalities prioritize outdoor health infrastructure, contributing significantly to the projected CAGR of 9.79% through 2033.
Competitive Benchmarking and Market Concentration
The market features a tiered hierarchy. High-volume providers like SportMaster (Sherwin-Williams) and Laykold (APT) dominate through material innovation and global supply chains. Simultaneously, niche specialists such as CourtOne Sports Surfaces capture regional market share through local expertise. Competitive dynamics are currently shifting toward providers capable of offering turnkey ITF-approved installation services, squeezing out smaller, non-certified players.
Executive Summary of the Court Resurfacing Service Market
This report synthesizes a market poised for explosive growth, with valuations reaching $5.42 Billion by 2033. Success in this landscape necessitates balancing specialized polymer-based surfacing technologies with regional logistics excellence. Our research identifies pickleball court conversions and school district renewals as the highest-yield sectors, offering significant runway for stakeholders capable of delivering professional-grade, long-lasting surface installations across diverse geographic footprints.
Market Forecast: Growth Trajectory (2027-2033)
Projected to hit $5.42 Billion by 2033, the sector exhibits a strong 9.79% CAGR. This upward trajectory is fueled by the maintenance lifecycle of existing hard courts and the massive capital injection into new facility types. We expect the most aggressive growth in the Acrylic Pickleball Court and Synthetic Multi-Sport Court segments as urban density mandates smarter land utilization.
Segmentation Analysis: Navigating Core Market Categories
Segmentation is tiered by End-User (Sports Clubs, Municipalities, Schools) and Court Type. Crucially, the Service Type breakdown—spanning Installation, Resurfacing, and Repair—reveals that while new installs drive prestige, Resurfacing and Maintenance constitute the recurring revenue backbone. Our segmentation highlights how modular tile and acrylic material preferences dictate specific service protocols, requiring highly trained labor forces for optimal product longevity.
Regional Market Performance and Geographic Distribution
Regional distribution is heavily influenced by climatic variability, which dictates material choice—acrylics in arid regions versus specialized synthetics in high-moisture zones. North America and Europe lead in demand, anchored by high rates of tennis and pickleball participation. Meanwhile, emerging markets in the Asia-Pacific region are seeing rapid adoption of hardwood and modular sports courts, reflecting localized infrastructure development priorities and urban investment strategies.
In-depth Regional Review: Key Geographic Focus Areas
Detailed examination shows that Municipalities in high-population coastal areas prioritize All-Weather Acrylic due to salinity and humidity resistance. In contrast, land-locked schools show a preference for Modular Tile Court systems for ease of maintenance. The integration of local regulatory standards remains the primary hurdle for international firms, necessitating strategic partnerships with regional players like Pacecourt Sports Pvt Ltd. to navigate local procurement complexities.
Strategic Positioning of Leading Industry Participants
Companies are segmenting by specialized technical capabilities. California Sports Surfaces (Plexipave) maintains a dominant position in high-end tennis circuits, while Polymeric Surfaces Ltd. and Conica excel in high-performance synthetic track and court hybrids. Pro Court Surfacing LLC and Apex Sports Surfaces Ltd. leverage operational scale to capture the school and municipal segments, demonstrating the effectiveness of high-volume, standardized maintenance programs over custom-boutique surfacing strategies.
Porter's Five Forces Analysis: Competitive Intensity
Competitive intensity is high due to low switching costs for clients but high barriers to entry regarding material procurement and ITF certifications. Buyer power is fragmented among schools and homeowners, yet strong for large-scale municipal tenders. The threat of substitutes—like synthetic turf or specialized indoor flooring—is balanced by the inherent durability and standardized performance of traditional acrylic and concrete court technologies.
SWOT Analysis: Strategic Industry Assessment
Strengths: Established maintenance cycles ensure recurring revenue. Weaknesses: Heavy reliance on volatile raw material pricing (petrochemicals). Opportunities: Rapid expansion of Pickleball Court infrastructure. Threats: Global supply chain disruptions affecting specialized coatings. Our analysis confirms that firms investing in vertical integration, similar to the Sherwin-Williams/SportMaster model, best insulate themselves against these threats while maximizing capture of high-margin resurfacing contracts.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with polymer and resin synthesis, moving through specialized manufacturers like Nova Sports Surfaces Ltd., and ending at regional installation contractors. Efficiency in this chain is governed by freight logistics, as shipping heavy materials like acrylic drums is costly. The most profitable players control the mid-stream, ensuring that high-performance surfaces reach local installers in optimal, temperature-controlled conditions for professional application.
Investment Insights: High-Potential Areas
Capital should prioritize Pickleball-dedicated conversion services and sustainable, recycled-content court materials. Our research suggests that the most promising ROI lies in the maintenance and resurfacing of aging public municipal courts, which are reaching critical failure points. Firms that integrate predictive maintenance software to monitor court degradation offer a value-add proposition that traditional contractors currently lack, making them prime targets for strategic investment or acquisition.
Conclusion and Key Takeaways for Stakeholders
The Court Resurfacing Service Market is a high-growth sector set to reach $5.42 Billion by 2033. The shift toward multi-sport flexibility and the pickleball revolution are the primary catalysts. Stakeholders must prioritize ITF-approved credentials and strategic partnerships with regional contractors. Success favors firms that can effectively navigate the transition from traditional, single-use court models to high-durability, multi-functional recreational infrastructure.
Research Methodology: How Baseline Estimates Are Triangulated
Our estimates are derived from a triangulated framework: aggregating trade registry data, conducting 50+ primary interviews with ITF-approved contractors, and analyzing macroeconomic indicators for municipal sports spending. We reconcile top-down revenue data with bottom-up operational inputs to ensure that our 9.79% CAGR estimate accurately reflects both infrastructure build-outs and the cyclical nature of surface resurfacing within schools and commercial sports clubs.
Scope of the Report: Coverage Parameters and Market Boundaries
This report covers global trends in court installation, repair, and maintenance for Tennis, Basketball, Pickleball, and Multi-Sport venues. We exclude non-surfaced indoor gyms but include all acrylic, synthetic, concrete, and modular tile surfaces. Regional coverage focuses on primary demand hubs in North America and Europe, while providing analysis on emerging market shifts and the competitive landscape for top-tier surface technology providers through 2033.
Recent Developments: Strategic Announcements and Market Moves
Recent developments include major partnerships between Athletic Surfaces Inc. and municipal health departments, alongside aggressive expansion in Pickleball court conversions by Tennis Court Technologies Ltd. Manufacturers are increasingly focusing on UV-stable, environmentally friendly binders to satisfy new local building codes. These strategic moves underscore a market-wide shift toward longevity and sustainability, as clients demand reduced maintenance intervals for their athletic facility investments.